
The Week Ahead in Forex: November 22 to November 27, 2026
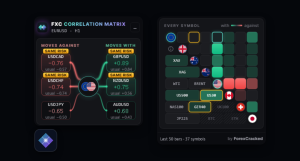
The dominant theme going into the week of November 22 to 27 is a risk-off tone. The risk meter reads -0.59 on a scale from -1 risk-off to +1 risk-on. Since our reference point, JP225 is down 10.06%, USTEC down 9.40%, XAUUSD down 8.88%, DE40 down 8.39%, US500 down 7.85% and US30 down 7.50%. Over the past 24 hours, JPY led currency strength at +0.78%, followed by CHF at +0.48%, while AUD was weakest at -0.73% and NZD slipped 0.31%. EUR, USD, GBP and CAD were all within a fraction of a percent of flat.
Recent releases set some context. Eurozone CPI y/y printed 4% against a consensus of 3.2%, and Core CPI y/y came in at 2.6% against 2.5%. CPI excl. Energy and Unprocessed Food y/y matched consensus at 2.2%. South African Retail Sales y/y came in at 2.4% against 3.5% expected, and m/m at -0.3% against -0.1%. US Initial Jobless Claims were 200K against 198K expected.
Tuesday brings the CB Consumer Confidence Index at 15:00 UTC, with consensus at 91.5 and previous at 91.7. Later, at 23:19 UTC, BoC Governor Macklem speaks, which is the main CAD event of the week. CAD strength was -0.10% over the last 24 hours.
Wednesday is the densest day. The session opens with Australia CPI q/q and the Monthly CPI Indicator y/y at 00:30 UTC, relevant given AUD’s -0.73% move. Germany GDP q/q follows at 07:00 UTC, with consensus and previous both at 0.2%. At 13:30 UTC the US releases a cluster: GDP q/q (consensus 3.4%, previous 3.4%), Core PCE Price Index y/y (consensus 3.1%, previous 3.1%), Core PCE m/m (consensus 0.3%, previous 0.3%), Durable Goods Orders m/m (consensus -0.7%, previous 1.8%), GDP Sales q/q (consensus 1.7%) and Initial Jobless Claims. New Home Sales follow at 15:00 UTC, consensus 0.739M against 0.676M previously, and the EIA Crude Oil Stocks Change arrives at 15:30 UTC.
Thursday opens with Australia Employment Change at 00:30 UTC, the second major AUD print in two sessions.
Positioning is unsettled. Retail books disagree by 37 points on USDCHF, 27 points on GBPUSD and 21 points on USDJPY. The crowd on BTCUSD flipped from 65% long to 51% short in 24 hours, and GBPCHF flipped from 56% short to 59% long. The US30 book moved 14 points toward long, while AUDJPY and GBPJPY each moved 8 points toward long, despite the weakness in equity indices.
The week’s data matters most if the Wednesday US releases and the Australian prints land far from consensus while the risk meter sits this deep in negative territory.
| At a glance | |
|---|---|
| Biggest moves since last week’s open | JP225 -10.06%, USTEC -9.40%, XAUUSD -8.88% |
| Currency strength, 24h | JPY strongest at +0.78%, AUD weakest at -0.73% |
| Risk meter | -0.59 (risk-off) |
Scheduled this week (High and Medium impact)
| Time | Ccy | Event | Impact | Consensus |
|---|---|---|---|---|
| Tue 15:00 UTC | USD | CB Consumer Confidence Index | High | 91.5 |
| Tue 23:19 UTC | CAD | BoC Governor Macklem Speech | High | – |
| Wed 00:30 UTC | AUD | Australia CPI q/q | High | – |
| Wed 00:30 UTC | AUD | Australia Monthly CPI Indicator y/y | High | – |
| Wed 07:00 UTC | EUR | Germany GDP q/q | High | 0.2% |
| Wed 13:30 UTC | USD | Core PCE Price Index y/y | High | 3.1% |
| Wed 13:30 UTC | USD | GDP q/q | High | 3.4% |
| Wed 13:30 UTC | USD | Durable Goods Orders m/m | High | -0.7% |
| Wed 13:30 UTC | USD | Initial Jobless Claims | High | – |
| Wed 13:30 UTC | USD | Core PCE Price Index m/m | High | 0.3% |
| Wed 13:30 UTC | USD | GDP Sales q/q | High | 1.7% |
| Wed 15:00 UTC | USD | New Home Sales | High | 0.739M |
| Wed 15:30 UTC | USD | EIA Crude Oil Stocks Change | High | – |
| Thu 00:30 UTC | AUD | Australia Employment Change | High | – |
Times are UTC. This brief describes measured market state and the published schedule. It is not financial advice and nothing in it is a trade recommendation.